
Quest Medical Indemnity
Independent medical indemnity for clinicians across the UK
Quest Medical Indemnity arranges medical malpractice and regulatory cover for consultants, clinics and group practices across the UK.
Who we are
A relationship, not just a renewal.
Quest medical Indemnity (QMI) specialises in arranging cover for clinicians in private practice. As an independent brokerage, we benchmark your cover across the market - which allows us to secure the best possible cover at the best possible price, based on your individual circumstances.
The QMI team bring deep expertise in insurance, with decades of experience arranging medical malpractice and regulatory cover for UK-based clinicians. Our managing director, Andy Foley, worked in healthcare settings for over three decades before moving into insurance - so, when it comes to the details of your clinical practice, we know the right questions to ask.
We value providing a personal and proactive service, backed by a thorough understanding of the clinical realities of your cover.

“
I’ve spent my career around surgeons, in and out of theatres, and I know the cover only matters if the person arranging it understands the work.
Andy Foley
Managing Director
Who we work with
Who we work with
Our clients are clinicians in private practice, along with the clinics and healthcare facilities they work through.
Clinicians starting private practice
Having supported many clinicians starting out in private practice, we anticipate the critical indemnity questions at the outset, with an outlook on your long-term needs.
Clinicians established in private practice
If you are busy and your time is short, the value of a broker is measured in their ability to secure the right cover at a competitive price, and how much friction they remove from your renewal process. We are serious about both.
Clinics and group practices
We arrange cover for clinics and group practices, to cover the facility itself as well as the clinical staff. This includes the lines which sit alongside indemnity, such as cyber and directors' and officers' cover.
We work across a huge range of surgical and medical specialties. Andy, our managing director, worked in healthcare for three decades before joining the insurance world. Whatever your speciality, we are dedicated to sourcing the most comprehensive and competitive terms available in the market.
The cover
What the cover actually includes
You might know it as medical indemnity. In the insurance market it is called medical malpractice insurance; professional indemnity written for clinicians to cover you for medical malpractice in the private sector.
The policies we place cover clinical claims as well as issues directly related to your practice which are not claims.

Cover for your practice in the private sector
Crown indemnity (now known as CNST) covers your clinical work with the NHS and stops there. Your private practice needs its own cover, and so does the work that sits in between, such as waiting list initiatives, where the position is not always as clear as it appears. This part of the policy responds when a claim is brought against you for clinical work outside Crown indemnity.
Protection for non-claim related matters
Not every threat to a clinician's career arrives as a negligence claim. A GMC referral, a coroner's inquest, a disciplinary process, or a matter outside your practice that nonetheless engages your registration, all require legal representation quickly. This part of the policy covers these non-clinical regulatory and legal expenses across both your NHS and your private practice, ground that Crown indemnity leaves entirely uncovered.
One policy, not a supplement to another
Both elements sit in the same policy. For most consultants that means it replaces defence organisation membership rather than running alongside it.
If you are currently with a defence organisation, there are some important structural differences which are set out in the next section.
Switching cover
Moving from a defence organisation: the difference that actually matters
Clinicians who have always been with a defence organisation rarely hesitate over price. They want to know that when moving to a contractual insurance policy, they have robust protection both for their past work and for future claims when they retire. It's a key question and deserves a straight answer.
How defence organisation cover is structured
Defence organisation cover is generally written on a losses occurring basis. A claim is assessed against the date of the incident rather than the date the claim arrives, so work done during your membership can in principle still be picked up after you leave. It is also discretionary, which means assistance is granted at the organisation's discretion rather than owed to you under a contract.
How commercial insurance is structured
A commercial policy is written on a claims made basis. It responds to claims made while the policy is in force. Because it is a contract of insurance, cover is guaranteed so long as the terms and conditions are met, rather than provided on a discretionary basis. Because claims in medicine can arrive many years after the event, the policies we arrange offer a minimum of 21 years of run-off cover upon retirement, for additional peace of mind.
Which is why run-off cover is built in, not sold later
The policies we place offer a minimum of 21 years of run-off cover on retirement, disability or death, which is priced into the premium from the start rather than offered as an additional purchase at the point you permanently cease practising. Claims arising from work carried out while you were insured remain covered for a minimum of 21 years afterwards, and your estate is covered if a claim is brought after your death, which does happen.
How we work
How we work
Every broker says they offer personal service. Here is what we actually mean by it, in the four places it makes a difference.
01
We are not tied to one insurer
We place business across the market rather than through a single insurer, which means your renewal is benchmarked each year rather than assumed. If your premium changes, we can tell you whether that is your practice, your claims history, or the market, because we are looking at more than one answer. We also have the option to seamlessly move you from one insurer to another if more competitive terms are available.
02
We treat your renewal as urgent, because your hospital does
If you hold practising privileges, your hospital wants your certificate of insurance well before your renewal date, and it will not let you book lists without one. A slow broker turns an administrative task into a problem for you and your patients. We start early, we chase, and we get the certificate to you so you are not left waiting.
03
Somebody reads your proposal form properly
Your proposal form is a statement of fact. If something is missing from it, an insurer can decline a claim on that basis years later, when it matters most. We go through it with you rather than passing it straight to an underwriter, because the things that get left off are almost never left off deliberately, and a five minute conversation is often all it takes to ensure that the information provided to insurers is complete.
04
You get a person, not a portal
you will always have access to a dedicated team member who knows your practice and will answer the phone when you need them. Just because renewal could be a completely online process, doesn't mean it should be.
Our team
Meet the Quest team.

Managing Director
Andy Foley
Andy spent over three decades in healthcare before he was a broker, spending a good deal of that time in operating theatres. when he explains a clinician's work to an underwriter, he is not just reading it off a form. Understanding what you actually do is the difference between cover that fits your practice and cover that approximately resembles it.
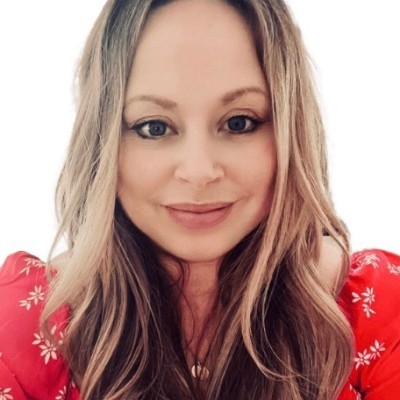
Account Director
Michelle Barratt
Michelle has spent 25 years in the insurance market, the last 14 specialising in medical malpractice. She started as a claims technician before moving into client-facing account work on large professional indemnity and medical malpractice accounts. Since 2012 she has worked alongside Andy, building a book of practitioners who wanted contractual cover rather than discretionary, most of whom have renewed year after year. At Quest she runs the renewal book day to day. Having prior experience in claims, she knows how a policy reads when it is tested, not just when it is sold.

Senior Broker
Bill Atkinson
Bill brings more than 20 years' experience in financial markets to Quest. He has worked directly with consultants across the medical profession, helping clinicians make sense of the financial and regulatory considerations that sit alongside their clinical practice.
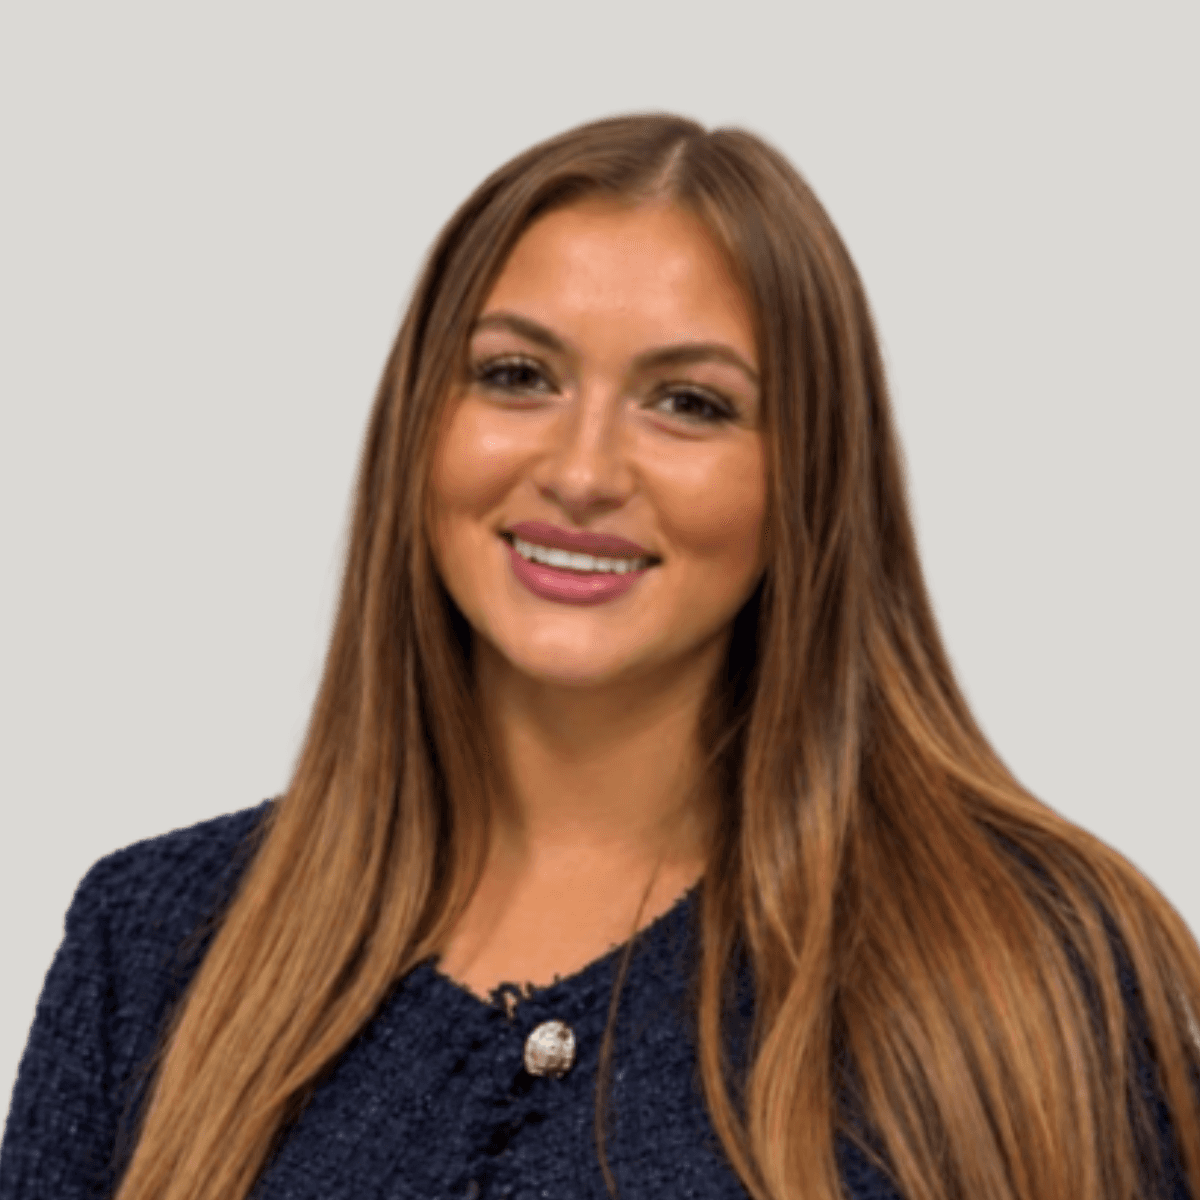
Medical Malpractice Broker
Lucy Molineaux
Lucy manages a portfolio of healthcare insurance accounts at Quest, including medical malpractice. Her work runs from understanding what each client actually needs through to negotiating their terms with insurers. Clients deal with her directly, so the person who negotiated their cover is the person they speak to when they have a question about it.

Broking Assistant
Lexie Bird
Lexie looks after the accounts side of new business and renewals: premiums, invoices, credit notes and payment queries, along with the documents that move between clients, insurers and underwriters. She also carries out compliance checks on new business and keeps the records that audit and regulation require. It is the part of the process clients only notice when it goes wrong, and Lexie's job is to make sure it doesn't.
Continuity, in practice
The people you speak to remain close to the work, the market, and the decisions that matter to your practice.
That continuity is the basis for advice that remains useful long after the first conversation.
Questions
Questions consultants ask
These are the questions that come up in almost every first conversation. If yours is not here, ask it directly.
Get in touch
Speak to us
Most of our clients arrive through someone who already uses us, so if a colleague passed on our name, let us know and we will pick up from there. Whether you are setting up in private practice, comparing what you already hold, or arranging cover for a clinic, the first step is a conversation.
Or, directly
Andy Foley, Managing Director — +44 7747 624080 · afoley@questmedicalindemnity.com
Already a client
For renewal forms and mid-term changes, contact the team using the form opposite.